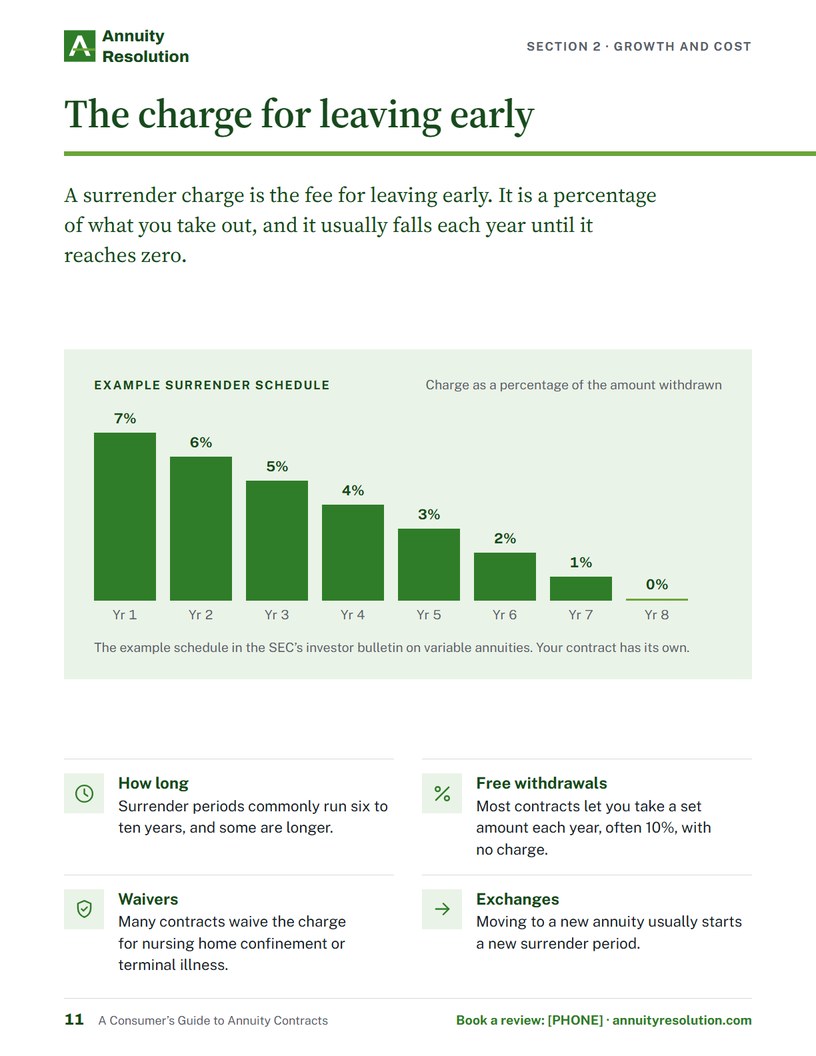
A surrender charge is the fee an insurance company charges if you take more than the allowed amount out of your annuity during the first years of the contract.
How the schedule works
Most schedules start at a percentage of what you withdraw and step down each contract year until they reach zero. A common pattern is 7% in year one, falling by one point a year. Yours may be longer, steeper or tied to each deposit rather than the contract date.
Where to find yours
- Open the contract and look for the “Surrender Charge” or “Withdrawal Charge” table, usually near the front in the contract data pages.
- Note the contract issue date on the same page.
- Count forward to the first year the charge shows 0%. That is your zero date.
Check for a market value adjustment. Some contracts add or subtract a separate adjustment on top of the surrender charge, depending on interest rates. It can make getting out cheaper or more expensive.
What else the charge affects
Surrender charges are only part of the cost of getting out. Taxes on gains, a 10% IRS additional tax before age 59½ and the loss of rider benefits can matter as much. A full review puts a number on each.
General information only, not legal or tax advice. Your contract governs.