Stuck in an annuity? Find out how to get out.
Built to put the annuity owner first.
In a free consultation, we review your situation and show you every way out, what each one would cost and whether there are red flags in how your annuity was sold. Nothing to sell you. No pressure.
Which one sounds like you?
If any of these fit, a free consultation is worth ten minutes of your time.
Stuck isn’t the same as trapped.
The agent who sold it won’t tell you this: most annuities have more exits than owners know about, and some cost nothing. We find every one in your contract and put a dollar figure on each.
- Your exact surrender charge today, and the date it reaches zero
- Penalty-free withdrawal amounts you can use right now
- The full cost of leaving: charges, taxes and any IRS penalty
Your contract, explained in plain English.
Annuity contracts run 40 pages or more. We read every one and tell you what you own, what it costs each year and what it really pays.
- What each rider costs and what it’s really worth
- Why your “benefit base” isn’t cash you can withdraw
- Caps, participation rates and fees, in plain numbers
If it was sold wrong, you may have rights.
Pressured into it? Told it was something it isn’t? Unsuitable and misrepresented sales can be challenged, and some claims have deadlines. Every client gets personal legal representation from an independent licensed law firm.
- Whether the sale fit your age, income and need for cash
- Whether a replacement reset your surrender clock
- Complaints and claims we can pursue on your behalf
Helping a parent? Start here.
Many of our calls start with an adult son or daughter. With your parent’s permission, we’ll walk you both through the contract and the choices.
- What we need to speak with you directly
- How to find the contract and statements
- Warning signs that make timing matter
When does your surrender charge hit zero?
Most owners don’t know. Get an estimate in ten seconds. Then talk it through with a Consumer Advisor in a free consultation.
- No email needed
- Based on the most common schedules
- Your real contract can differ, so we check it
Estimate only. Assumes a schedule that starts at 7% or 10% and falls 1 point a year, on a full surrender. Market value adjustments, taxes and free-withdrawal amounts are not included. Your contract governs.
A written review you can actually read.
Not a sales illustration. A plain-language report from our review team, yours to keep and share with family or your accountant.
- Contract summaryWhat you own, in one page.
- Your surrender clockToday’s charge and the date it reaches zero.
- Rider and fee auditWhat each costs per year, and whether it’s worth it.
- Every option, pricedSide by side, in dollars, including keeping it.
- Our recommendationThe path we would take, and any red flags in the sale.
 Annuity Review · Confidential
| Option | Cost today | Notes |
|---|---|---|
| Keep, revisit May 2027 | $0 | Charge ends in 7 months |
| Free withdrawal | $0 | Up to 10% a year |
| 1035 exchange | $4,200 | New clock starts |
| Surrender now | $11,850 | Plus tax on gain |
Three steps. No pressure at any of them.
Free consultation
A short call with a Consumer Advisor. You’ll know if we can help, and what it would cost, before you commit to anything.
Step 1We read every page
Surrender schedule, fees, riders, tax position and how it was sold. We can request the contract for you.
Step 2We help you act
Every option with its real cost, then we help you carry out the one you choose: out, exchanged, or kept on your terms.
Step 3Every annuity has more than one way forward.
Most owners are told two: keep paying or pay to leave. These are all six we price for you.
Keep it, with eyes open
Know your dates and what your riders are worth. Often the right answer.
Penalty-free withdrawals
Many contracts allow a portion out each year with no surrender charge.
Exchange it (1035)
Move without a tax bill, but only if the new contract truly beats the old.
Surrender it
Know the full cost first: charge, adjustments, taxes and any IRS penalty.
Use your free-look period
Most states give you a short window to cancel for a refund. Act fast.
Challenge how it was sold
You may have legal remedies, and some have deadlines. Don’t wait on this one.
Cost and timing are general guides. Your review prices each option for your contract.
The question is who the attorney represents.
Our job is to read your contract, tell you what it says and explain what you can do about it. That is all we are paid for.
- Nothing to sell youNo annuities, no insurance, no investments.
- Paid by you, not by commissionYou see any fee in writing before any work starts. No commissions from anyone, ever.
- Personal legal representationEvery client enters a separate attorney-client relationship with an independent licensed law firm, confirmed in writing. That attorney represents you. Not Annuity Resolution, not the sales team and certainly not the insurance company.
 Annuity Resolution
Most owners are leaving money and rights on the table.
We look for these in every contract. The agent who sold yours had no reason to point them out.
Money you can take out this year, penalty-free
Many contracts let you withdraw a portion every year with no surrender charge. Most owners never use it.
A year in rider fees you may not need
Income and death-benefit riders are often charged every year, whether you ever use them or not.
Your surrender charge drops to zero
Leave a year early and it can cost thousands. Wait a few months and it may cost nothing. We find your exact date.
If it was sold the wrong way
Unsuitable or misrepresented sales can be challenged. Some claims have deadlines, so timing matters.
Get my free consultationCommon findings, not promises. What we find depends on your contract.
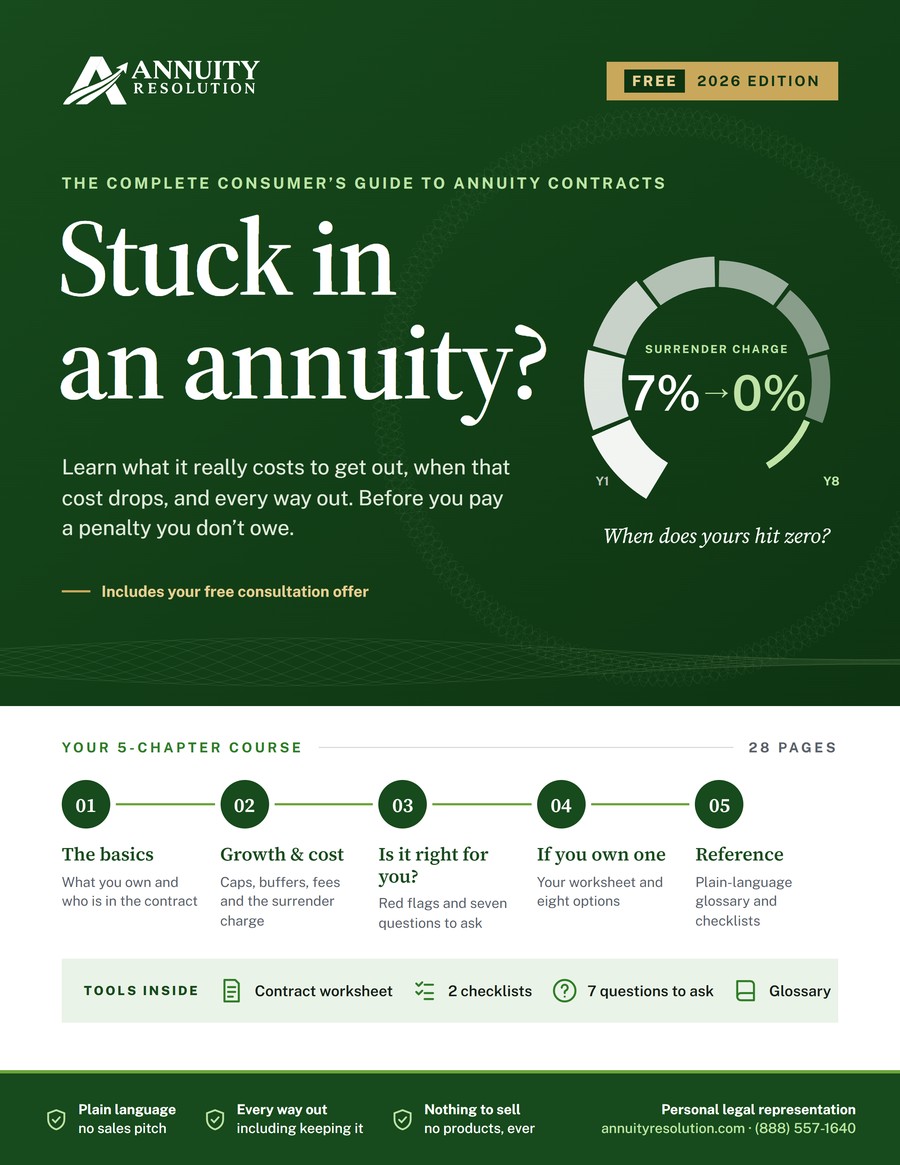 FREE2026 edition
The annuity guide the insurance companies won’t send you.
What it really costs to get out, when that cost drops, and every way out. Written for owners, by a company with nothing to sell.
- What it costs to get out, year by year
- The date your surrender charge hits zero
- The “benefit base” that isn’t your money
- 7 red flags in how annuities are sold
- 8 ways out, including penalty-free options
- A worksheet for your own contract
Free, 28 pages. No sales calls. Unsubscribe any time.
Plain-language guides for annuity owners.
Straight answers.
Don’t see yours? Call and ask. A real person answers, never a call center.
Can I really get out of my annuity?
Is the consultation really free?
What do I need to get started?
How long does it take?
Can you help if I’m calling about a parent?
Is my information kept confidential?
Waiting costs you.
Rider fees come out every year. Free-look windows close in days. Some legal claims have deadlines. The consultation is free, so there’s no reason to wait.
Find out if you can get out. Free.
Send the short form. Our office will call you promptly, with no cost and no obligation.
- Every way out, and what each one costs
- Whether your annuity was sold the wrong way
- If we can’t help, we’ll tell you on the first call
- Confidential. Nothing to sell you
Request your free consultation
The secure request form loads here on the live site.
Prefer to talk? Call us at (888) 557-1640.